Cost overview
| Item | Amount |
|---|---|
| Notarisation (standard template, 1 shareholder) | approx. €60–110 |
| Certification of the commercial register application | approx. €40–70 |
| Commercial register entry | approx. €150 |
| Trade registration | €20–60 |
| Share capital (recommended) | from €500–2,000 |
| Realistic total | approx. €300–450 plus capital |
With a low share capital, notary costs fall, because the value of the transaction is based on the capital. However, the GNotKG (Court and Notary Costs Act) sets minimum values, so fees cannot fall indefinitely.
Why €1 in share capital is a bad idea
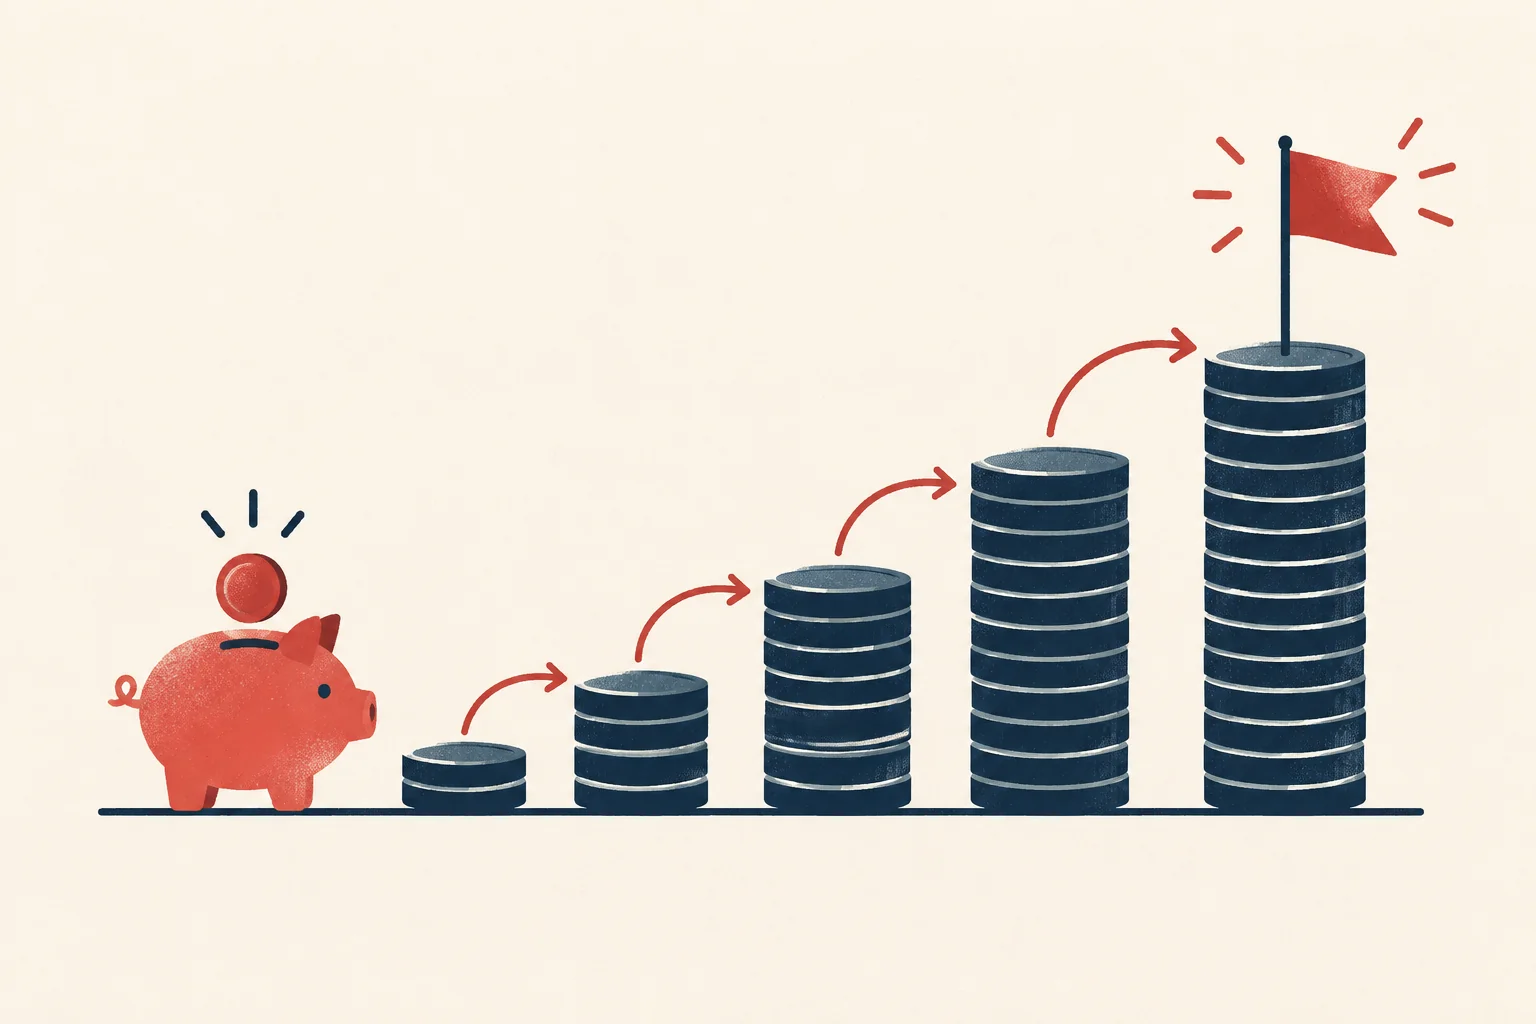
Formally, one euro is sufficient. In practice, this immediately creates a balance-sheet over-indebtedness as soon as the first invoice arrives — formation costs, register fees and advice exceed the capital many times over. At least €1,000 to €2,000 is advisable, so the company can bear the start-up costs itself.
The retention obligation
The UG must transfer 25 percent of its annual net profit to a statutory reserve each year until the share capital reaches €25,000. Only then is conversion into a GmbH possible — it is permitted, but not compulsory. The reserve is not available for distribution.
Ongoing costs
- Bookkeeping and annual financial statements: from around €1,200 per year
- IHK membership fee: from around €30–150 depending on the chamber and profit
- Publication of the annual financial statements: around €50
- Bank account, insurance, and payroll processing where applicable
Ongoing costs barely differ from those of a GmbH — the UG is cheaper to form, but not cheaper to run.
When the GmbH is the better choice
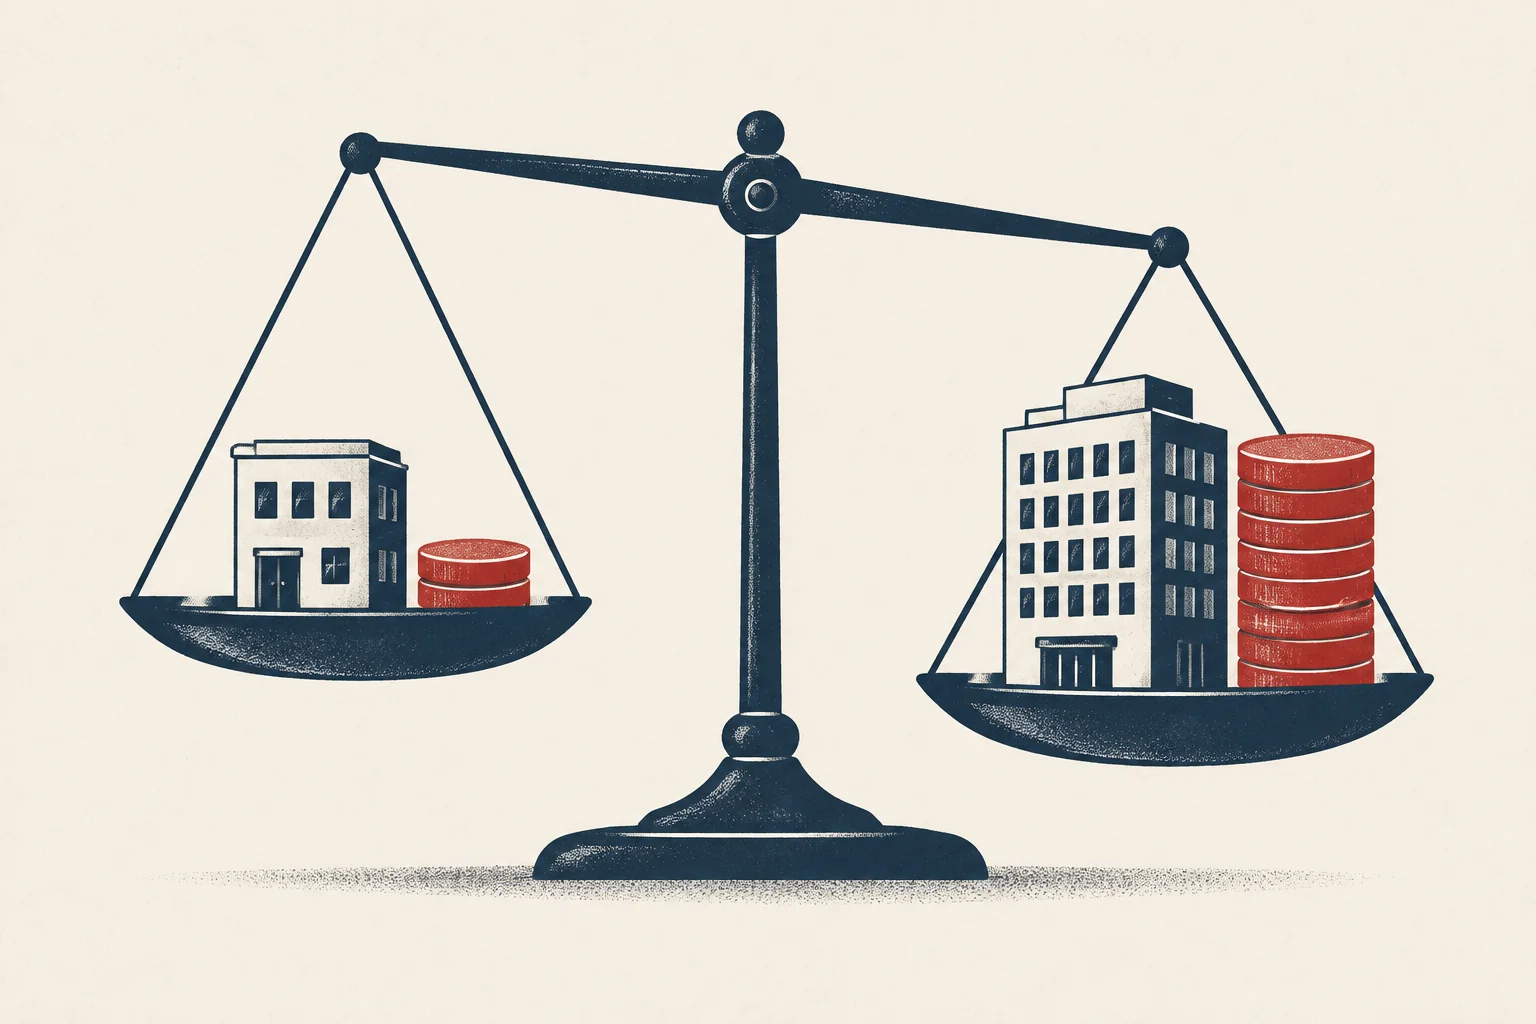
If you can raise €25,000, there is much to be said for the GmbH: a better image with banks and major customers, no retention obligation, and no later conversion with fresh notary costs. The UG is the right choice when capital is tight and limited liability needs to be established quickly.
After registration
After registration, the tax registration questionnaire follows, along with registration with the trade association (Berufsgenossenschaft) and — if you employ staff — the company number (Betriebsnummer). Much of this is done in writing, and deadlines run from the date the letter is received.
The reserve in numbers: an example
If a UG earns an annual surplus of €20,000, § 5a(3) GmbHG requires a quarter — €5,000 — to go into the statutory reserve. This money may not be distributed to shareholders. Any loss carried forward from the previous year is deducted first.
| Annual surplus | Mandatory reserve (25%) | Maximum distributable |
|---|---|---|
| €8,000 | €2,000 | €6,000 |
| €20,000 | €5,000 | €15,000 |
| €40,000 | €10,000 | €30,000 |
The reserve obligation has no time limit and applies until the UG becomes a GmbH through a capital increase to at least €25,000. The conversion itself again costs notary and register fees.
Checklist before deciding
- How high are your start-up costs for the first months — does the planned capital cover them?
- Do banks, landlords or major clients expect a GmbH?
- Should profits be paid out early or stay in the company?
- Is a later conversion to a GmbH planned?
The process is explained in forming a UG step by step; for comparison see the cost of forming a GmbH. Write letters to authorities and partners in the letter editor.