Bonus, Gratifikation, premium — the differences
A Gratifikation (gratuity) typically rewards company loyalty, for example as a Christmas or holiday bonus. A bonus is performance- or success-related and tied to targets. A premium rewards a specific occasion, such as an improvement suggestion. The label used is not legally binding — what matters is the substance of the agreement.
Tax treatment: other remuneration (sonstiger Bezug)
For payroll tax purposes, one-off payments are classed as sonstige Bezüge (other remuneration) and are taxed according to the annual wage tax table. This often results in a high deduction in the month of payment, but this evens out again through the income tax return or the annual payroll tax adjustment. Explain this to your employees in advance — it saves queries.
Social security and the March rule (Märzklausel)
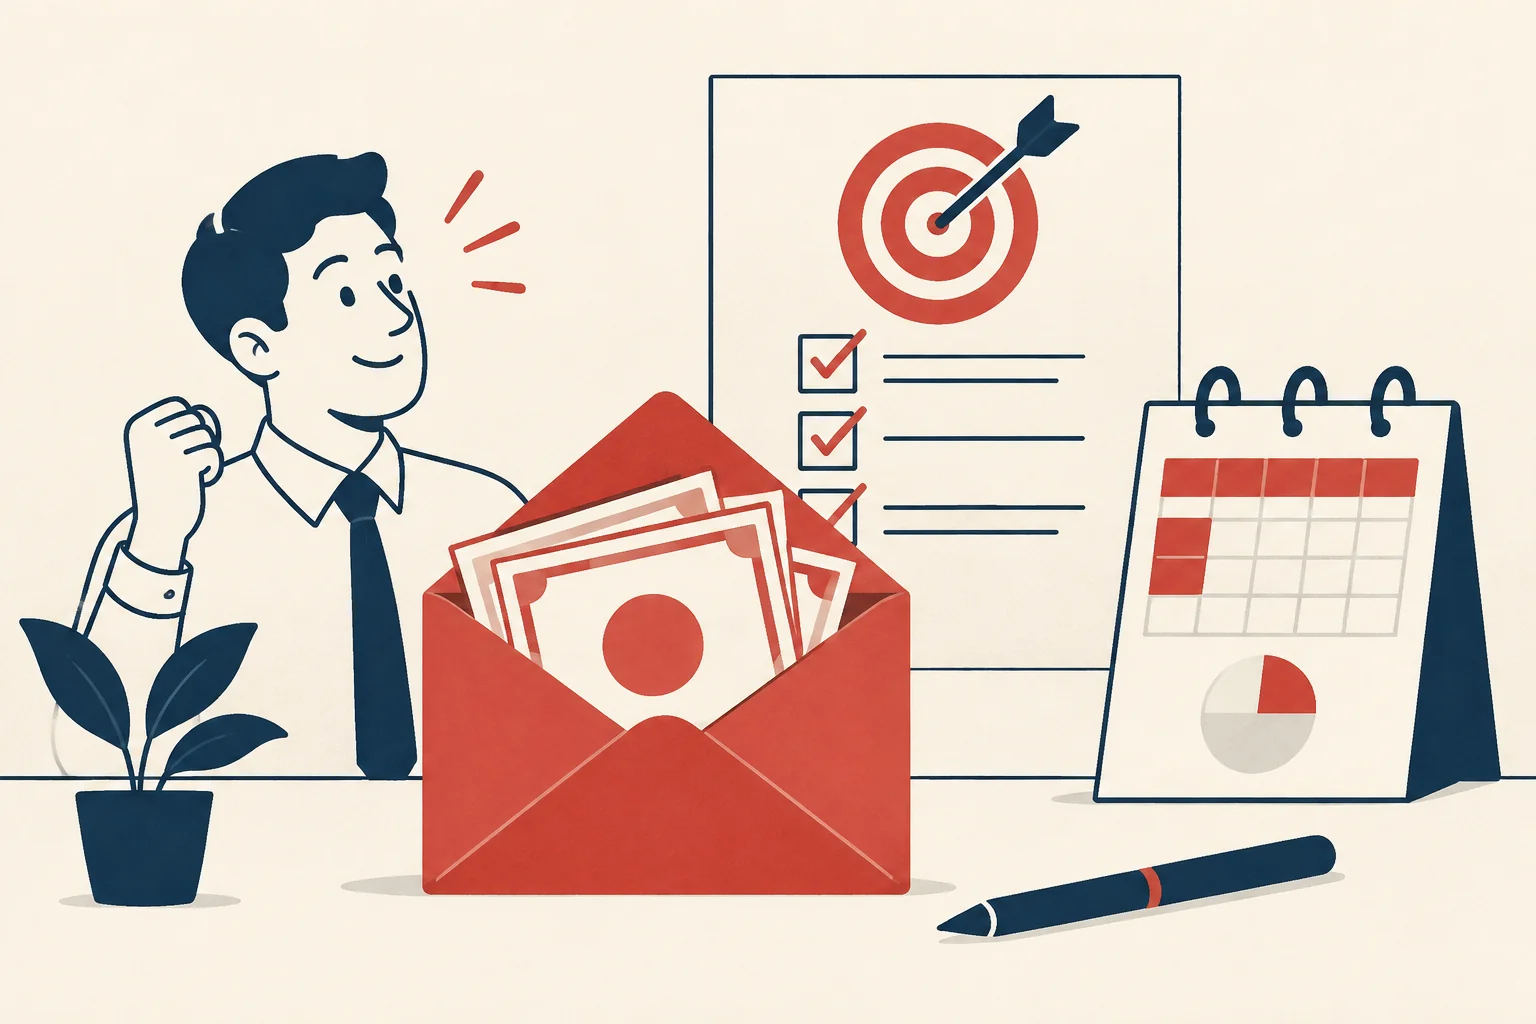
One-off payments are subject to contributions insofar as the pro-rata annual contribution assessment ceiling is not exceeded. If a one-off payment is made between January and March and is not fully subject to contributions in the current year, it must be allocated to the previous year under the Märzklausel (March rule). Check this point with every spring payment — it is the classic audit finding.
Reservation of voluntariness and established company practice
If you pay a gratuity three times in the same way without reservation, an established company practice (betriebliche Übung) arises: the entitlement then also exists for the future. A valid reservation of voluntariness (Freiwilligkeitsvorbehalt) must be worded clearly and unambiguously, and must not be mixed with a reservation of revocation — otherwise, under the case law of the Federal Labour Court (Bundesarbeitsgericht), the clause is invalid in its entirety.
Cut-off date and repayment clauses
| Clause | Permissible? |
|---|---|
| Tying a pure loyalty-based gratuity to a cut-off date | generally yes |
| Cut-off date clause for a performance-related bonus | generally invalid |
| Repayment for a gratuity below €100 | not permitted |
| Commitment until 31 March of the following year for a gratuity of up to one month's salary | common and usually permissible |
Target agreements as the basis
For success-related bonuses, the target agreement must be concluded in good time. If the employer fails to set targets, it can become liable for damages — courts then often assume 100 percent target achievement. Set targets in writing, ideally in the first quarter of the relevant period.
What should go into the notification
- The relevant period and basis of calculation
- Gross amount and payment date
- Legal basis: employment contract, works agreement or individual commitment
- Reservations, provided they are legally permissible and clearly worded
A short, cleanly worded bonus letter for each employee is better documentation than any group email — and belongs in the personnel file.
Calculating an annual bonus step by step
- Check entitlement: legal basis, targets, achievement and cut-off date.
- Calculate the gross amount and record it as a non-recurring payment.
- Wage tax using the annual table (annual pay with and without the bonus).
- Social security: check the pro-rata annual contribution ceiling; for payments up to 31 March, the March clause.
- Document: file the bonus notice, calculation and payslip in the personnel record.
What the bonus notice should contain
State the reference period, agreed targets, achievement in percent, gross amount and payout month. Only add reservations that legally fit the payment; for contractually promised performance bonuses, a voluntary reservation is usually ineffective. Have clauses reviewed by an employment lawyer if in doubt.
Write the notice in the letter editor and send it as a letter so a dated, signed version exists. Layout basics are in the DIN 5008 template guide.